CANADA’S PROPOSED CAPITAL GAINS INCLUSION INCREASE WAS COUNTERPRODUCTIVE
ARTICLE SUMMARY
I reflect on my concerns about Canada’s 2024 proposal to increase the share of capital gains included in taxable income. The corrected article distinguishes an inclusion rate from a tax rate and records the proposal’s cancellation, while preserving my original perspective on investment and business growth.
KEY TAKEAWAYS
The 2024 proposal concerned an inclusion-rate increase, not a 67% capital gains tax rate.
The updated article notes that the proposal was cancelled in March 2025.
Correction and update: October 19, 2026. The 2024 proposal concerned increasing the capital gains inclusion rate from one-half to two-thirds, not imposing a 67% tax rate. The government cancelled the proposal in March 2025. The general inclusion rate remains one-half under section 38 of the Income Tax Act. My concerns below reflect my opinion on the original proposal.
DEAR CANADA: A TWO-THIRDS CAPITAL GAINS INCLUSION RATE?
In 2024, Canada proposed increasing the share of capital gains included in taxable income from one-half to two-thirds for corporations and most trusts, and for individuals’ annual capital gains above $250,000. This was an inclusion-rate proposal, not a 67% tax rate: income tax would then be calculated at the applicable rate. As a business owner, I was concerned about what the proposal could mean for investment and growth.
From my perspective, the proposed change could have served as a major deterrent for both foreign investors and Canadian businesses. Higher taxes on capital gains might slow down growth and innovation, making it less appealing for entrepreneurs to invest in Canada. The impact stretches beyond personal finances. Corporations too could have felt the pressure of paying a larger portion of their gains in taxes, potentially limiting their expansion and job creation capabilities.
This is not a matter of political debate between Liberals and Conservatives. Instead, it’s about how much of our hard-earned money we’re willing to give away and how these policies could shape Canada’s economic future. Is this the right path to take? How will it affect our ability to compete on a global scale?
As someone considering further expansion in Canada, the proposed changes made me think twice about investing in resources like land, warehousing, and people. It’s essential to ask ourselves: How much are we willing to sacrifice in terms of growth and investment opportunities for the sake of government revenue?
What are your thoughts on this? Let's start a conversation!
“This move could serve as a major deterrent for both foreign investors and Canadian businesses. Higher taxes on capital gains might slow down growth and innovation, making it less appealing for entrepreneurs to invest in Canada. ”
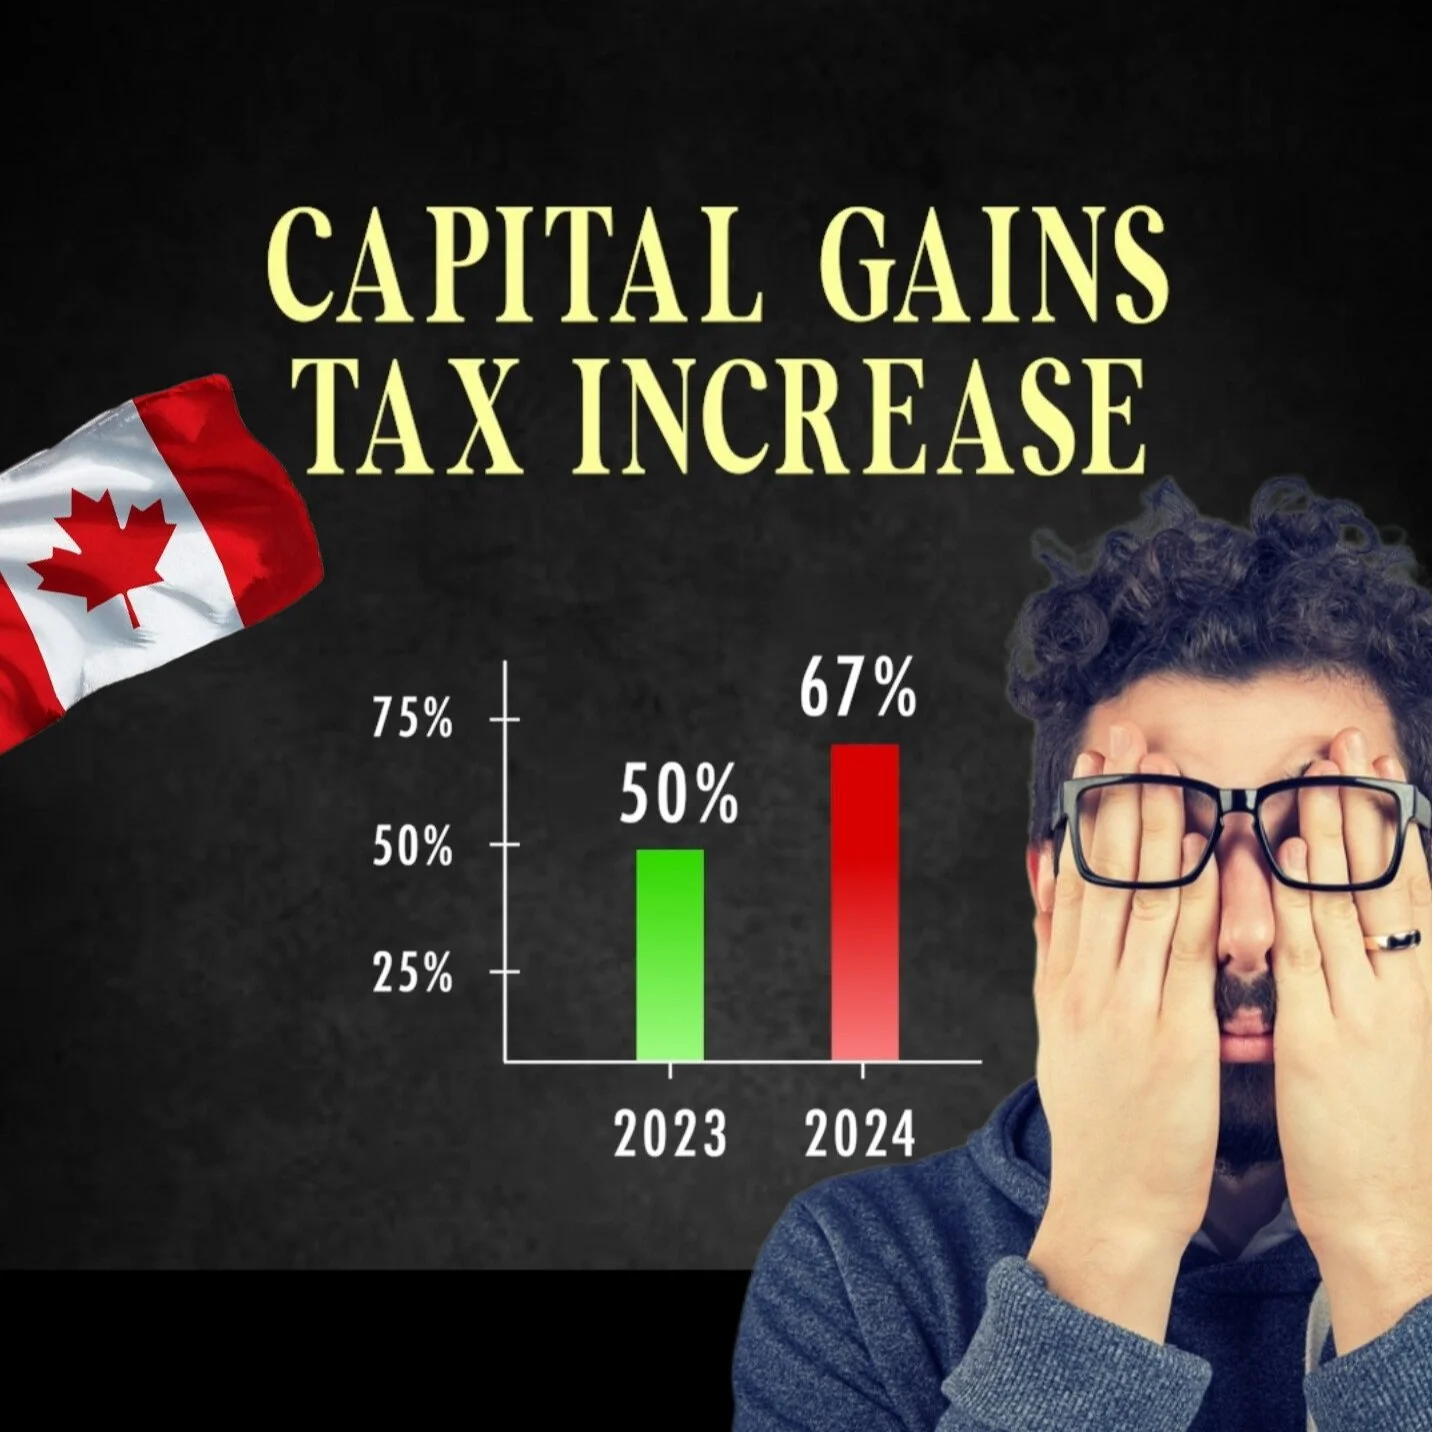
This archival graphic illustrates Canada’s 2024 proposed capital gains inclusion-rate increase, which was cancelled in 2025.
WHY DID CANADA PROPOSE THE CAPITAL GAINS INCLUSION INCREASE?
Canada’s 2024 proposal was presented as a way to raise revenue and increase tax fairness. It concerned the share of a gain included in taxable income, not a change from a 50% tax rate to a 67% tax rate.
Under the proposal, the two-thirds inclusion rate would have applied to corporations and most trusts and to individuals’ annual capital gains above $250,000. The government argued that the additional revenue could support public services and other priorities.
At the time, the government defended the proposed changes, while critics argued that they could discourage investment and growth, particularly in sectors reliant on capital investment. My concern was that higher taxation of gains could make Canada less competitive as investors compared opportunities across markets.
The proposal was part of a debate about revenue, fairness, and economic growth. It was later cancelled in March 2025.
DIFFERENCE BETWEEN CONSERVATIVE AND LIBERAL/SOCIALIST POLICIES?
Conservative vs. Liberal/Socialist Policies: A Comparative Overview
Conservative Policies:
Economic Freedom: Conservatives tend to prioritize free markets and limited government intervention in the economy. They believe that reducing taxes, cutting government spending, and deregulating industries encourage private enterprise and entrepreneurship, which in turn leads to economic growth.
Taxation: Conservatives advocate for lower taxes, especially for businesses and higher-income individuals, arguing that this stimulates investment, job creation, and overall economic growth. They prefer a trickle-down approach, where wealth generated by the upper class benefits the broader society.
Role of Government: Conservatives emphasize limited government. They believe that government should play a minimal role in everyday life and business, and that individual freedoms and responsibilities should be prioritized over government control.
Social Issues: Conservatives often support traditional values. This includes positions on family structure, marriage, and religious freedom. They may oppose liberal policies on issues such as abortion and LGBTQ+ rights based on moral or religious grounds.
National Defense: Conservatives typically advocate for a strong national defense, supporting higher military spending to ensure national security. They emphasize the importance of a powerful military to protect national interests both domestically and internationally.
Liberal/Socialist Policies:
Economic Equality: Liberals and socialists focus on reducing economic inequality by increasing government intervention in the economy. This can include progressive taxation, where higher earners pay more, and social safety nets to support the less fortunate.
Taxation: Liberals typically support higher taxes on corporations and the wealthy to fund social programs like healthcare, education, and welfare. Socialists may go further, advocating for the redistribution of wealth to ensure greater economic equality.
Role of Government: Liberals and socialists believe in a larger role for government in providing services that benefit the public, such as universal healthcare, public education, and environmental protection. Socialists, in particular, may support the nationalization of key industries (e.g., energy, healthcare) to ensure that these services are run in the interest of the public rather than for profit.
Social Issues: Liberals tend to support progressive social policies, advocating for individual rights and freedoms, such as abortion rights, LGBTQ+ rights, and gender equality. They emphasize diversity and inclusion as important societal values.
National Defense: While liberals generally support a strong national defense, they often prioritize diplomatic solutions over military intervention and advocate for reduced military spending in favor of funding domestic programs. Socialists are even more likely to advocate for demilitarization and non-interventionist foreign policies.
Summary of Key Differences:
Economic Policies: Conservatives advocate for free markets and less regulation, while liberals and socialists favor government intervention to address inequality.
Taxation: Conservatives push for lower taxes, while liberals and socialists support higher taxes on the wealthy to fund social programs.
Role of Government: Conservatives prefer limited government involvement, whereas liberals and socialists believe in a larger, more active government to address social and economic issues.
Social Policies: Conservatives uphold traditional values, while liberals and socialists push for progressive reforms and inclusivity.
Defense: Conservatives emphasize military strength, while liberals and socialists often prioritize diplomacy and reducing military expenditure.
These ideological differences shape the contrasting policies of conservative and liberal/socialist groups in various countries, including the U.S., Canada, and Europe.
EXAMPLES OF CAPITAL GAINS TAX RULES IN DIFFERENT COUNTRIES
The examples below summarize selected rules for individuals, checked October 19, 2026. Tax treatment differs by asset, account, residency, exemptions, and reliefs, so these figures are not a uniform comparison of every capital gain. Official sources are linked below.
1. Denmark
Ordinary share income (2026): 27% or 42%.
Ordinary share income, including dividends and share gains, is taxed at 27% on the first DKK 79,400 in 2026 and 42% on the excess. Qualifying spouses have a doubled threshold; separate investment-account rules apply.
2. Finland
Taxable capital income: 30% or 34%.
Taxable capital income is taxed at 30% up to €30,000 annually and 34% on the excess. The threshold concerns total taxable capital income, including taxable capital gains, rather than each individual sale.
3. France
Standard private securities gains (2026): 31.4% PFU.
Private securities gains generally face the standard 31.4% PFU in 2026: 12.8% income tax plus 18.6% social levies. Taxpayers may elect the progressive income-tax scale; property gains and special arrangements follow different rules.
4. Sweden
Listed share gains: generally 30%.
Gains on listed shares outside tax-favoured accounts are generally taxed as capital income at 30%. Qualifying private-home gains effectively face 22%, while investment savings accounts use annual deemed-income taxation.
5. Ireland
Standard CGT: 31% for disposals on or after October 7, 2026.
The standard CGT rate fell from 33% to 31% for disposals on or after October 7, 2026. Development-land gains remain at 33%; exceptions and reliefs apply.
6. Norway
Share gains and dividends (2026): 37.84%; other capital income: 22%.
Personal share gains and dividends face an effective 37.84% rate in 2026, while other capital income generally faces 22%. The distinction depends on the type of income and applicable rules, rather than an ordinary income-bracket scale.
7. Spain
General savings-income rates: 19%–30% from 2025.
Under the common-territory individual income-tax regime, gains from asset disposals generally enter the savings tax base. The top 30% rate applies only to the portion above €300,000, rather than the whole gain.
8. Japan
Covered share and securities gains: generally 20.315%.
Individual gains on shares and covered securities generally face 15% national income tax, a reconstruction surtax equal to 2.1% of that national tax, and 5% local tax. Other assets, accounts, and exemptions follow different rules.
9. Canada
General inclusion rate: 50% of a gain, taxed at applicable income-tax rates.
Generally, half of a capital gain is included in taxable income and taxed at applicable income-tax rates. This is an inclusion rate, not a 50% tax rate. The proposed two-thirds inclusion increase was cancelled in March 2025.
10. Australia
Eligible individual gains: income-tax rates, with a potential 50% discount after 12 months.
As of this October 2026 review, the general 50% CGT discount can apply to eligible individuals and trusts after an asset is held for at least 12 months. Companies cannot use this general discount, and foreign-resident restrictions apply.
11. Germany
Private investment income: generally 26.375% combined, before church tax.
Private investment income, including many securities gains, generally faces 25% tax plus a solidarity surcharge equal to 5.5% of the tax: 26.375% combined before applicable church tax. Property and business gains can follow different rules.
These examples cover different tax bases and asset regimes. Exemptions, reliefs, account types, and holding periods can change the result, which is why headline percentages need context.
Official sources, checked October 19, 2026: Denmark · Finland · France · Sweden · Ireland · Norway · Spain · Japan · Canada · Australia · Germany
George Stroumboulis sits down with Garrett Patten, entrepreneur, filmmaker, producer, and fourth-generation business leader. They discuss his journey from the Caterpillar boardroom to Hollywood films, the realities of building a multigenerational business, the economics behind filmmaking, and what it takes to reinvent yourself and succeed in an entirely new industry.